Fast Facts
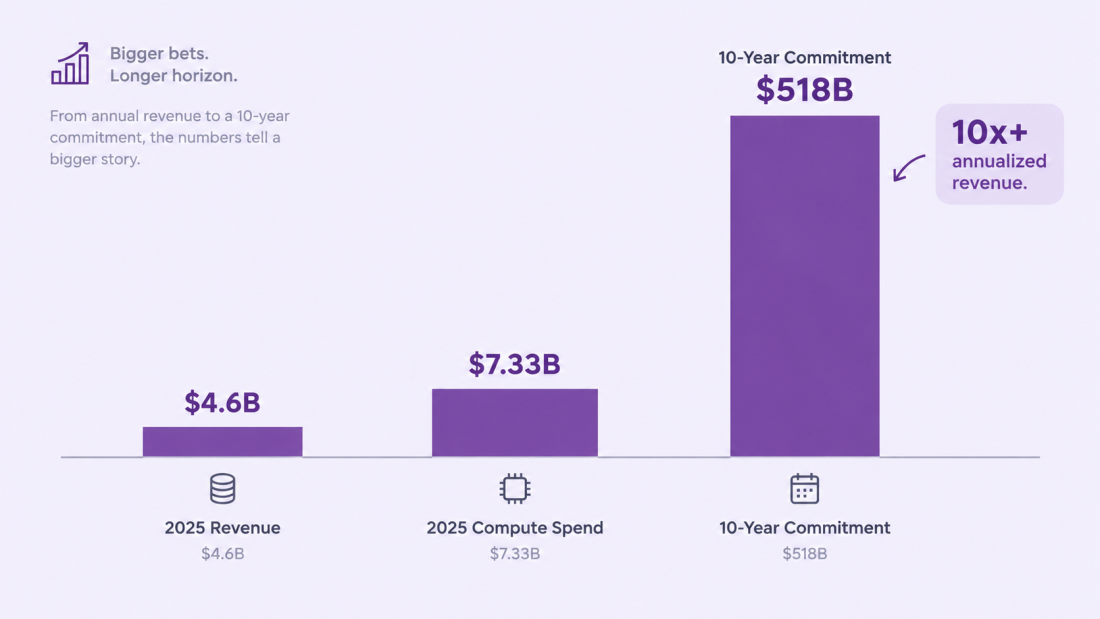
A leaked draft of Anthropic’s IPO prospectus, reported by Reuters on September 28, shows Anthropic compute spend hit $7.33 billion in 2025, roughly $1.60 for every dollar of the $4.6 billion in revenue the company brought in that year. Operating losses reached more than $8 billion, and the company has committed $518 billion to cloud and infrastructure obligations over the next decade, against 2025 revenue that was a fraction of one year of that commitment.
Revenue is genuinely accelerating — Q2 2026 alone brought in $11.5 billion, more than the entire 2025 total — and Anthropic says it posted an operating profit for a second straight quarter. The spend-to-revenue ratio is the number worth tracking as Anthropic heads toward a reported $2 trillion IPO target, because it’s the same ratio every infrastructure-heavy AI vendor now has to answer for.
Anthropic compute spend became public for the first time when Reuters and the Financial Times obtained details from the company’s confidential S-1 filing, prepared in June ahead of a planned IPO. The numbers show a business growing extraordinarily fast and spending even faster to sustain it. 2025 revenue reached $4.6 billion, up roughly twelvefold from $400 million in 2024. Full-year operating expenses came to about $12.65 billion, of which compute and infrastructure spending alone was $7.33 billion — nearly three times the 2024 figure and 58% of total operating costs. Anthropic is a PBC backed by Amazon (NASDAQ:AMZN), Google (NASDAQ:GOOGL), Nvidia (NASDAQ:NVDA) and Microsoft (NASDAQ:MSFT), each of which also supplies it with cloud and chip capacity.
Why Anthropic Compute Spend Hides Behind a Misleading Loss Number
The headline figure making the rounds is a $42 billion net loss for 2025, more than five times 2024’s loss. That number is a poor proxy for how the business is actually performing: roughly $34 billion of it comes from a non-cash accounting charge tied to convertible financing instruments, not cash leaving the business. Strip that out and the operating loss — spending on compute, staff and overhead against revenue actually collected — comes to just over $8 billion, itself still nearly the size of the company’s entire net loss the year before. See our analysis where we explain why CoreWeave’s revenue data revealed a 7-year bet on 3-month deals.
Verified numbers
| Stat | Detail |
|---|---|
| $7.33B | 2025 Anthropic compute spend on compute and infrastructure — roughly 3× the 2024 figure |
| $4.6B | 2025 revenue, up ~12× from $400M in 2024 — the base Anthropic compute spend is measured against |
| $518B | Long-term cloud, compute and infrastructure commitments across six partners |
The $518 Billion Question Behind Anthropic Compute Spend
That commitment figure is a multi-year total spread across six infrastructure partners, not a single year’s bill, but it still dwarfs anything the company has generated to date — more than ten times its annualized run rate even at the fastest recent growth point. Most of that obligation stands whether or not the capacity actually gets used, which is the structural risk every AI lab making decade-long compute commitments now carries on its books. Customer concentration adds to the exposure: roughly a quarter of 2025 revenue came from just two customers, neither locked into long-term contracts. See our analysis where we explain why Micron’s take-or-pay memory contracts lock in $100B with no cancellation clause.
Anthropic is “a total dog of a company,” said Ed Zitron, CEO of EZ Primary Research and a longtime AI critic, pointing to the widening operating loss.
The Case Against the Bear Case
The counter-argument is real and shouldn’t be waved away: Q2 2026 revenue alone hit $11.5 billion, up from $4.73 billion in Q1, and the Financial Times reported the company is on track to close the current quarter with an adjusted operating profit for a second straight period. A business whose quarterly revenue has roughly doubled twice in six months is not purely a cost story. The question isn’t whether Anthropic compute spend looks alarming next to 2025’s full-year revenue — it’s whether 2026’s growth trajectory can keep outrunning commitments signed years in advance. See our analysis where we explain why NVIDIA’s AI compute revenue hit $40 billion while memory costs already squeeze it.
⚠️ Hypothetical scenario (illustrative only, not a reported case)
An African enterprise software vendor signs a multi-year API contract with a frontier AI lab, pricing its product on the assumption per-token costs keep falling the way they have for two years. The lab’s own compute-to-revenue ratio, similar to what Anthropic’s filing shows, later forces a mid-contract pricing renegotiation. The vendor’s margin model, built on a cost curve it never controlled, gets rewritten mid-year.
What This Means for Anyone Pricing AI Into a Budget
Every enterprise building long-term plans around a frontier AI vendor’s API pricing is implicitly betting that vendor’s own spend-to-revenue math works out. Anthropic’s filing is the clearest public look yet at what that math looks like inside a leading lab, and it shows margin pressure persisting even at twelvefold revenue growth. Buyers locking in multi-year AI contracts should ask vendors how their own infrastructure commitments compare to current revenue, not just today’s price per token. See our analysis where we explain why model deprecation is the contract risk nobody negotiates and why nobody can agree on the industrial AI market’s real size.
💡 CreedTec Analyst’s Note by Daniel Ikechukwu
Strategic Impact
Anthropic’s filing turns an industry-wide suspicion into a disclosed number: frontier AI labs are spending well over a dollar on compute for every dollar of revenue, funded by commitments that outlast any single year’s growth.
Stop / Start / Watch
- Stop: treating a lab’s revenue growth rate alone as evidence its unit economics are sound.
- Start: asking AI vendors for their own compute-spend-to-revenue ratio before signing a multi-year contract.
- Watch: whether Anthropic’s reported operating profit in recent quarters holds as the $518 billion in commitments starts coming due.
ROI Outlook
The IPO, reportedly targeted for mid-November at close to a $2 trillion valuation, will be the first time public markets get to price this ratio directly rather than infer it from leaks. Whatever multiple investors assign will become the benchmark every other AI infrastructure story gets measured against.
— Daniel Ikechukwu
Budgeting for AI infrastructure costs?
Get CreedTec’s weekly briefing on AI vendor economics, compute pricing and procurement risk, written for teams signing multi-year contracts. Subscribe free.
Sources
- Fortune: “Anthropic’s $2 trillion IPO prospectus has leaked” (Sept 29, 2026)
- SiliconANGLE: “Leaked Anthropic IPO filing reveals $8B operating loss, rapid revenue growth” (Sept 29, 2026)
- The Ringer: “The Numbers Behind Anthropic: An FAQ” (Sept 30, 2026)
- The Deep Dive: “A Leaked Anthropic Prospectus Shows Explosive Growth, A Widening Loss” (Sept 2026)
- TradingKey: “Anthropic IPO: What Investors Need to Know After Draft Prospectus Leak” (Sept 2026)